Simplifying the mortgage process

Let us guide you through the process of finding a mortgage that meets your unique needs.
GET STARTED

Mortgage financing can be confusing, it doesn't have to be, here's the plan.

Get started right away

The best place to start is to connect with us directly. The mortgage process is personal. Our commitment is to listen to all your needs, assess your financial situation, and provide you with a clear plan forward.

Get a clear plan

Sorting through all the different mortgage lenders, rates, terms, and features can be overwhelming. Let us cut through the noise, we'll outline the best mortgage products available, with your needs in mind.

Let us handle the details

When it comes time to arranging your mortgage, we have the experience to bring it together. We'll make sure you know exactly where you stand at all times. No surprises. We've got you covered.
Lee Welbanks

Principal Broker/Owner

Lee is a pro­fes­sional and pas­sion­ate cham­pion for his cus­tomers. Peo­ple who meet him soon under­stand the many ben­e­fits of mak­ing their all-important mort­gage deci­sions through an accred­ited mort­gage bro­ker who is work­ing for them.


After four years of full-time study, Lee grad­u­ated the Uni­ver­sity of Toronto in 1995 with a Bach­e­lor of Busi­ness Admin­is­tra­tion (BBA), Spe­cialty in Finance. He imme­di­ately began mort­gage lend­ing in Toronto for a major Cana­dian finan­cial insti­tu­tion where he acquired the depth of finan­cial plan­ning knowl­edge to step out on his own.


Lee’s cus­tomer ser­vice is ongoing; after the clos­ing the trans­ac­tion he looks out for his cus­tomers, ensur­ing they con­tinue to lever­age mar­ket­place intel­li­gence, the chang­ing reg­u­la­tory envi­ron­ment and smart financ­ing strate­gies to reduce debt and save interest. As a Reverse Mortgage specialist, he guides Canadian homeowners who are planning for retirement through this unique solution of accessing the equity in their home as a financial planning strategy.


And if pas­sion, per­spec­tive and moti­va­tion aren’t enough, Lee is a mem­ber in excel­lent stand­ing of Mortgage Professionals Canada.


Lee Contact Lee any time to arrange a con­fi­den­tial mort­gage dis­cus­sion and review your financ­ing options.

Here are some nice things clients have said about working with us.

Looking to run some numbers?

Mortgage Calculator

A simplified and easy to use mortgage payment calculator, for purchase renewal, or refinance.

CALCULATOR
Whatever your needs, I have the home financing solutions for you.

Mortgage financing for Older Canadians in Retirement.

  • Providing opportunities so you can enjoy your life and benefit those you love.
  • Reverse Mortgages - everything you need to know to access the equity in your home as a financial planning strategy.
LEARN MORE

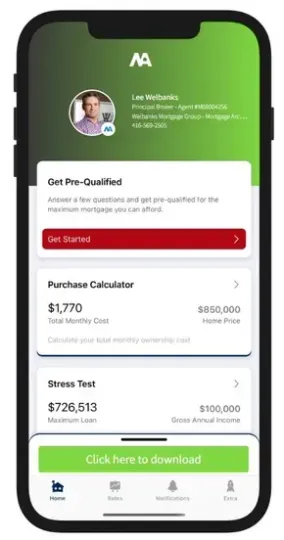
Download My Mobile App


WHAT CAN YOU DO WITH MY APP


  • Calculate your total cost of owning a home
  • Estimate the minimum down payment you need
  • Calculate Land transfer taxes and the available rebates
  • Calculate the maximum loan you can borrow
  • Stress test your mortgage
  • Estimate your Closing costs
  • Compare your options side by side
  • Search for the best mortgage rates
  • Email Summary reports (PDF)
  • Use my app in English, French, Spanish, Hindi and Chinese
 

Go ahead and schedule a meeting with me!

BOOK A CALL

Articles to keep you learning

By Lee Welbanks • November 4, 2026
Mortgage Options During Divorce or Separation: What You Should Know If you’re going through—or considering—a divorce or separation, you may not realize that there are mortgage solutions specifically designed to help one party keep the home . For many people, the family home is their largest asset and where most of their equity is tied up. In situations like this, a spousal buyout program can allow one person to refinance the property and buy out the other party’s share—often up to 95% of the home’s value . This option can work whether you want to keep the home or your former partner does. What Is the Spousal Buyout Program? The spousal buyout program is a refinancing option that allows one owner to purchase the other owner’s share of the property as part of a separation or divorce settlement. In some cases, it can also be used to pay off jointly held debts, as outlined in a legal agreement. Below are some of the most common questions about how the program works. Is a finalized separation agreement required? Yes. Lenders require a signed and finalized separation agreement that clearly outlines how assets and debts are to be divided. This document is essential for approval. Can the funds be used for renovations or personal debts? No. Funds from a spousal buyout can only be used to: Buy out the other owner’s share of equity Pay off joint debts specifically listed in the separation agreement They cannot be used for renovations, personal loans, or unrelated expenses. How much equity can be accessed? The maximum amount available is the amount required to: Buy out the other party’s agreed-upon share of equity Pay off any joint debts listed in the agreement This amount cannot exceed 95% loan-to-value . What is the maximum loan-to-value allowed? The maximum loan-to-value is the lesser of : 95%, or The remaining mortgage balance plus the required buyout and joint debt payout The property must be the primary owner-occupied residence . Do all parties need to be on title? Yes. All individuals involved in the buyout must currently be registered on title. Your solicitor will confirm this through a title search. Does this only apply to married or common-law couples? No. While commonly used for married or common-law couples, the program may also apply to siblings or friends who jointly own a property and need one party to exit the mortgage. These cases are typically reviewed on an exception basis and require insurer approval. If no separation agreement exists, the purchase contract must clearly outline the buyout terms. Is a full appraisal required? Yes. A physical, on-site appraisal is required to confirm the property’s value before the mortgage can be finalized. Final Thoughts This overview covers some of the most common questions about mortgage options during separation or divorce, but every situation is different. Working with an independent mortgage professional gives you access to multiple lenders, specialized programs, and unbiased advice—so you can clearly understand your options and choose what’s best for your future. If you’re navigating a separation and need guidance around keeping or selling the home, feel free to connect anytime. All conversations are handled with discretion and confidentiality, and I’d be happy to walk you through your options.
By Lee Welbanks • October 28, 2026
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.
By Lee Welbanks • October 21, 2026
You’ve outgrown your current home. It no longer fits your life, so moving makes sense. And you’re not interested in juggling two properties. Selling first and buying something new feels like the right move. Ideally, you want possession of the new home before leaving the old one. That overlap makes moving easier, reduces stress, and gives you time to paint, renovate, or settle in before the boxes arrive. But there’s a common challenge. What if the down payment for your next home is tied up in the equity of the one you’re selling? That’s where bridge financing comes in. How bridge financing works Bridge financing temporarily unlocks equity from your current home once it has a firm sale . It bridges the gap between selling your existing property and purchasing your next one, allowing you to use that equity toward your down payment. What about competitive markets? In a hot market, a strong offer often means a larger deposit . If you don’t have that cash sitting in your account, but you do have equity, a deposit loan can help you compete with confidence. The non-negotiable requirement To qualify for bridge financing or a deposit loan, your current home must have a firm, unconditional sale . No firm sale = no bridge or deposit loan. Lenders need certainty to calculate available equity and manage risk. Bottom line A firm sale is the key that unlocks bridge financing and deposit loans. If you’re planning a move and want to understand how these options could work for you, let’s talk. I’m always happy to walk you through your options and help you plan your next step with confidence.
Show More